


Fast · Simple · Trusted
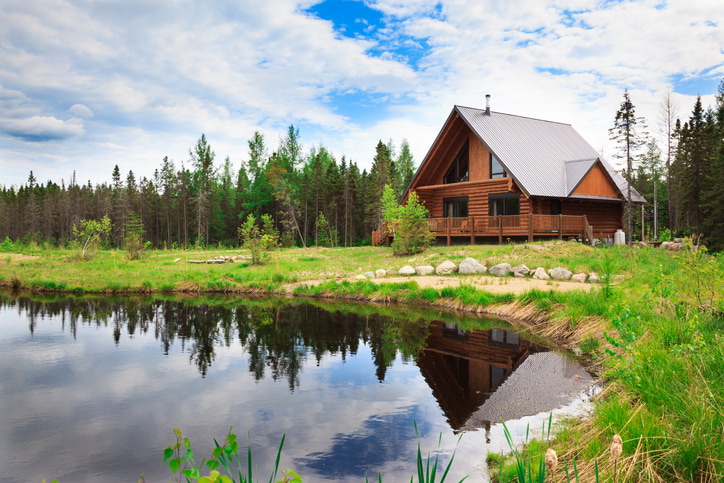
Cottage Insurance in Gravenhurst for Every Season at the Lake
 100% Canadian Owned

13,000+ Reviews Across Western | 4.5
BUILT AROUND YOUR PROPERTY
Start With How You Use Your Cottage
Every cottage has its own rhythm. Maybe yours opens on the May long weekend and closes after Thanksgiving, or maybe you head up for snowy winter weekends too. Either way, a recreational property faces different risks than your everyday home.
How often you're there, Muskoka's changing weather, your time on the water and the stretches when no one's around can all shape the coverage that makes sense for you.
A good policy looks at the whole picture: the building, what's inside it, your liability and any extras that make sense for your spot on the lake.
Cottage Coverage
What Does Cottage Insurance Cover?
Coverage depends on your insurer, your property and the policy you choose. Here are the main protections worth talking through with your broker.
Cottage Building Coverage
Building coverage can help pay to repair or rebuild your cottage after a covered loss. Your limit should reflect what it would actually cost to rebuild, not just what the property might sell for.
Construction materials, the building's age and how easy it is to reach can all affect coverage and eligibility.
Contents and Personal Belongings
From the couch by the woodstove to the paddleboards in the shed, your cottage holds more belongings than you might think.
Contents coverage can help protect eligible items from insured losses, subject to your policy limits, exclusions and deductibles. It's worth asking whether valuables or gear stored outside need extra protection.
Personal Liability Coverage
Personal liability coverage can help protect you financially if you're legally responsible for injuring someone or damaging their property.
With family and friends coming and going all summer, this one matters. Review your limits and mention features like docks, swim rafts or steep paths to the water.
Detached Structures
Plenty of cottages come with a detached garage, a shed, a bunkie for the kids or a boathouse down by the water.
Ask whether each one is covered, what limits apply and whether how it's built or used affects eligibility.
Docks and boathouses
Check waterfront structures individually rather than assuming they share the same protection as the cottage. Ask about covered causes of damage, limits and exclusions. Boats and other watercraft should be discussed separately.
SEASONAL PROPERTY COVERAGE
Seasonal Cottage Insurance in Gravenhurst
Lots of Gravenhurst cottages are busiest from spring to fall, then sit quiet under the snow all winter. If that sounds like yours, tell your broker when you're usually up there and who keeps an eye on the place once you've headed home.

Depending on your policy, it's worth talking about:
- How you winterize, and whether the heat stays on.
- Shutting off the water and draining the pipes.
- Who checks on the cottage, and how often.
- Locks, alarms and other ways to keep it secure.
- When you need to tell your insurer it'll be empty for a while.
- What happens if a pipe freezes and bursts.
A seasonal cottage may not have the same coverage as a year-round home, so confirm any occupancy requirements before you lock up for the;
Waterfront Cottage Insurance in Gravenhurst
Life on the water is a big part of the Muskoka draw. If your cottage sits on or near a lake, take a closer look at how your policy handles water-related risks.
A few things to bring up:
- Overland water coverage: Can help when lake levels rise or heavy rain floods in, depending on your policy and eligibility.
- Sewer backup coverage: Can help if water backs up through your drains or septic connection and causes damage.
- Boathouses and docks: Check whether they're included, what they're insured for and what's left out. Ice damage is a good one to ask about.
- Shoreline and outdoor property: Retaining walls, stone steps and landscaping aren't always treated the same way as the cottage, so it's worth confirming.
- Storm damage: Muskoka summer storms can roll in fast. Ask how wind and hail damage is handled and which deductibles apply.
Coverage for docks, shoreline features and boats can vary quite a bit, and sewer backup and overland water are separate coverages with their own limits and deductibles. Rather than assuming, ask your broker exactly what's included for your property.
Ready to Save on Cottage Insurance in Gravenhurst?
Get a personalized quote in minutes.
No obligation · Average savings of 750 per year · Licensed in Ontario
Cost Factors
What Affects the Cost of Cottage Insurance in Gravenhurst?
A simple summer cabin and a four-season lakefront home won't have the same premium. Your price reflects the cottage itself, where it sits and the coverage you choose.
Here's what insurers usually look at:
Your cottage insurance premium depends on your coverage limits, optional protection, deductibles and claims history. The best way to determine your cost is to request a personalized quote using accurate details about your cottage.
Why Western
Why Choose Western Financial Group?
You don’t need to arrive with all the answers. A Western broker can walk you through available policies in plain language, from limits and exclusions to your responsibilities when no one is at the cottage.
Proudly BBB Accredited with an A+ Rating
We’re accredited by the Better Business Bureau (BBB), which means we meet high standards for trust, transparency, and customer service.
Advice for changing cottage plans
Cottage life changes over time. Whether you’re renovating, adding a bunkie, welcoming renters or spending more time there in winter, your broker can help you review how those plans affect your insurance needs.
Support with claims questions
Western can help you navigate the claims process and connect with the appropriate insurer contact. Your insurance company determines coverage and the claim outcome.
13,000+ Reviews Across Western | 4.5
Michael M.
Ontario, Canada
★★★★★
We contacted Western for a cottage insurance quote and had questions about our dock and bunkie. The broker walked us through the coverage and limits without rushing us
Sandra M.
Toronto, Ontario
★★★★★
Western helped us compare our cottage insurance quote with our existing policy. Looking at the deductibles and water coverage made the differences much easier to understand
Steve T.
Brampton, ON
★★★★★
We wanted to find the best cottage insurance for how we use our property. The Western broker explained the options and what we needed to check when closing up for winter.
FAQ
Frequently Asked Questions
Explore More
Other Insurance Products
Home Insurance
Protect your Ontario home, condo, or property with comprehensive coverage.
Renters Insurance
Affordable coverage for renters with protection for belongings and liability.
Business Insurance
Commercial coverage tailored to your industry and operations.
Travel Insurance
Coverage for medical emergencies, trip cancellations, and lost baggage.