


Fast · Simple · Trusted
Cottage Insurance in Muskoka for Your Place by the Lake
 100% Canadian Owned

13,000+ Reviews Across Western | 4.5
BUILT AROUND YOUR PROPERTY
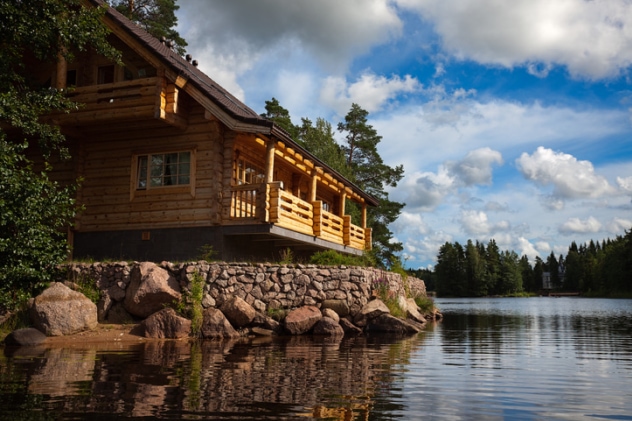
Cottage Insurance for the Way You Spend Time in Muskoka
Maybe you arrive by boat, follow a private road to a summer cabin or enjoy your lake house year-round. Each comes with different insurance needs, and your coverage should reflect the way you spend time there.
Think beyond the main building to your guest bunkie, belongings and waterfront structures. Your broker can help you see what’s included, what may need extra protection and what you’ll need to do between visits to keep your coverage in place.
Cottage Coverage
What Can Muskoka Cottage Insurance Cover?
Policies vary, so it’s worth checking how each part of your property is protected. Your cottage, belongings and other structures may have separate coverage limits.
Your Cottage Building
Building coverage may help pay to repair or rebuild your cottage after a covered loss. The amount should reflect rebuilding costs, not its selling price. Custom woodwork, stone fireplaces, older construction and getting materials to an island can all affect that estimate.
Furniture and Personal Belongings
Furniture, appliances and the belongings you leave at the cottage can add up. Check your contents coverage, including any special limits. If you bring items from home for the summer, ask which policy covers them.
Personal Liability Coverage
Welcoming friends and family is part of cottage life. If a guest is accidentally injured at your cottage or you accidentally damage someone else’s property, personal liability coverage may help with legal defence costs and covered damages if you’re held legally responsible, subject to your policy’s terms.
Bunkies and Detached Structures
A guest bunkie or storage shed is part of your cottage property, too. Tell your broker about each building and how you use it, including sleeping accommodation or rentals, so you can review the protection available.
Docks and Boathouses
Don’t overlook the structures at the water’s edge. Confirm whether your dock and boathouse are insured, how much coverage they have and which types of damage are excluded. A boat needs its own coverage review, even when it’s kept in an insured boathouse.

BEFORE YOU CHOOSE A POLICY
Insurance Questions That Matter for Muskoka Cottages
Water Damage and Flood Coverage for Muskoka Cottages
Water damage isn’t all treated the same way. A burst pipe, a backed-up sewer and water flowing over dry land can fall under different policy provisions. Some protection may be optional or unavailable for your property, so it’s important to know the difference before a loss happens.
Ask your broker:
- Which water losses are included?
- Is optional overland water or sewer backup protection available?
- What limits and deductibles apply?
- How are docks, boathouses and belongings near the shoreline treated?
- What exclusions or maintenance conditions should I understand?
Muskoka’s floodplain maps can be a useful starting point for understanding flood exposure. They don’t tell you whether a property qualifies for insurance or whether a particular loss would be covered.
Ready to Save on Cottage Insurance in Muskoka?
Get a personalized quote in minutes.
No obligation · Average savings of 750 per year · Licensed in Ontario
Cost Factors
How Much Does Cottage Insurance Cost in Muskoka?
There’s no one-size-fits-all price, but you may want to budget between $1,400 to $2,800 per year for cottage insurance in Muskoka. Many factors impact that price, like a boat-access cabin may cost a different amount to insure than a four-season cottage near town. Your premium depends on the property, how you use it and the coverage you choose.
Factors insurers may consider include:
Look beyond the price when comparing quotes. Check what each policy covers, what it leaves out and how a claim would be paid. Your deductible is the amount you pay toward a covered claim, so make sure it’s manageable for you.
How to Find Affordable Cottage Insurance in Muskoka
Keeping insurance affordable starts with finding coverage that fits, not simply choosing the lowest price. Your broker can help you explore potential savings:
-
Ask About Bundling
Combining eligible home, auto, and cottage insurance policies may qualify you for multi-policy discounts. -
Discuss Protective Devices
Ask whether monitored security alarms, water-leak detection systems, or other protective features may help reduce your premium. -
Report Property Improvements
Let your broker know about updates to your roof, heating system, electrical wiring, or plumbing, as these improvements may positively affect your insurance costs. -
Choose a Manageable Deductible
Selecting a higher deductible may lower your premium, but it should remain an amount you can comfortably afford if you need to make a claim. -
Review Your Policy at Renewal
Regularly update your property details and review your coverage to ensure it continues to meet your current needs.
Discounts, savings opportunities, and eligibility requirements vary by insurer and policy.
Why Western
Why Work With Western Financial Group?
For more than a century, Western Financial Group has delivered trusted, people-first protection to over a million Canadians. We believe in doing insurance the right way, with integrity, care, and community at heart.
Proudly BBB Accredited with an A+ Rating
We’re accredited by the Better Business Bureau (BBB), which means we meet high standards for trust, transparency, and customer service.
That commitment has earned us national and regional recognition across employer culture, customer experience, innovation, and social impact. Our awards reflect the quality of our service, the strength of our team, and the depth of our engagement in communities coast to coast.
13,000+ Reviews Across Western | 4.5
Michael M.
Ontario, Canada
★★★★★
We contacted Western for a cottage insurance quote and had questions about our dock and bunkie. The broker walked us through the coverage and limits without rushing us
Sandra M.
Toronto, Ontario
★★★★★
Western helped us compare our cottage insurance quote with our existing policy. Looking at the deductibles and water coverage made the differences much easier to understand
Steve T.
Brampton, ON
★★★★★
We wanted to find the best cottage insurance for how we use our property. The Western broker explained the options and what we needed to check when closing up for winter.
FAQ
Frequently Asked Questions
Explore More
Other Insurance Products
Home Insurance
Protect your Ontario home, condo, or property with comprehensive coverage.
Renters Insurance
Affordable coverage for renters with protection for belongings and liability.
Business Insurance
Commercial coverage tailored to your industry and operations.
Travel Insurance
Coverage for medical emergencies, trip cancellations, and lost baggage.