


Fast · Simple · Trusted
Cottage Insurance in Parry Sound
 100% Canadian Owned

13,000+ Reviews Across Western | 4.5
BUILT AROUND YOUR PROPERTY
Start With How You Use Your Parry Sound Cottage
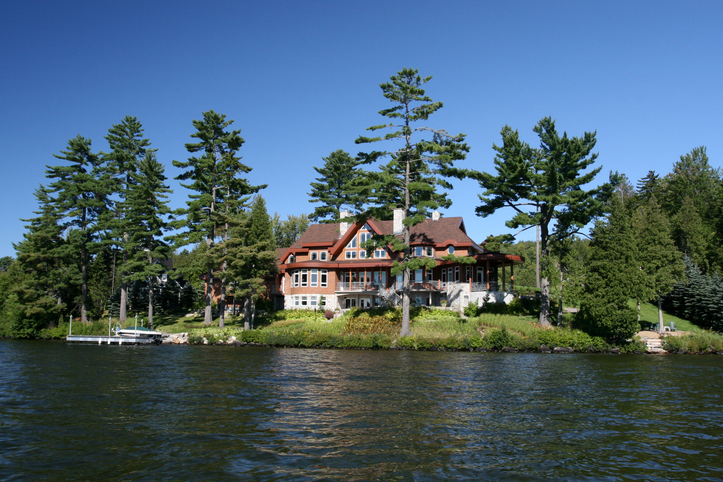
Every cottage has its own rhythm. Yours might open with the first warm weekend and close after Thanksgiving, or welcome you back for winter getaways. Perhaps there’s a bunkie for family visits or a dock reached only by boat. Those everyday details matter when choosing insurance.
Start with a conversation about how you get there, how you heat it and who stays. Information about detached buildings, waterfront features and your plans for the coming year helps your broker identify suitable options and explain what an insurer needs to know.
Cottage Coverage
What Can Cottage Insurance Cover?
Think beyond the cottage walls to the belongings, outbuildings and gatherings that make the property yours. Here are the main protections to review. Your policy determines which losses are insured and how a claim would be settled.
Cottage building
Building coverage may help pay to repair or reconstruct your cottage after an insured loss, such as a fire that damages the living area and roof, subject to your deductible, limits and settlement terms. Discuss building materials, renovations, custom features and site access when establishing an appropriate limit.
Belongings kept at the cottage
Contents coverage may help pay to repair or replace furniture, appliances, clothing and other belongings damaged by an insured loss, according to your policy. Bedroom furniture and kitchen appliances alone can represent a substantial replacement expense. Ask about special limits for valuables and how belongings brought from your primary home are insured.
Personal liability
Personal liability coverage may help with covered damages and legal defence costs if you are legally responsible for injuring someone or damaging their property, such as when a visitor is injured by a poorly maintained exterior step that breaks. Ask how coverage applies to guests, the property’s features and any rental use.
Bunkies and detached buildings
Garages, sheds and guest bunkies may be eligible for coverage, including repairs to a storage shed damaged by a windstorm if both the structure and the cause of damage are insured. Identify each building separately, explain how it is used and confirm its insured limit, exclusions and settlement terms.
Docks and boathouses
Check waterfront structures individually rather than assuming they share the same protection as the cottage. Ask about covered causes of damage, limits and exclusions. Boats and other watercraft should be discussed separately.
SEASONAL PROPERTY COVERAGE
Seasonal Property Insurance in Parry Sound
Closing the cottage shouldn’t mean leaving insurance questions unanswered. A property that sits empty for several months may need different coverage and precautions from a secondary home you visit regularly. Share your seasonal routine so your broker can explain the options and conditions that apply.

When requesting a quote for your cottage, talk to your broker about:
- Opening and closing dates: When the cottage is normally occupied.
- Winter arrangements: Whether it remains heated or its plumbing is winterized.
- Property checks: Who visits between stays and what checks are completed.
- Access: Whether road or water access changes during the year.
- Heating equipment: Primary and supplementary heat sources.
- Changes in use: Plans for longer stays, renovations or rentals.
Before you turn the key for the season, confirm your insurer’s requirements for property checks, heating and plumbing. A general inspection schedule or winterizing routine may not satisfy every policy condition.
Rental Cottage Insurance in Parry Sound
Sharing your cottage with guests can help make the most of the weeks you’re not there. It can also change your insurance needs, even for an occasional rental. Before advertising or accepting bookings, tell your broker how you plan to rent it.
When exploring rental cottage insurance in Parry Sound, explain:
- How many days or weeks you expect to rent the property.
- Whether rentals are short-term or longer seasonal stays.
- Whether you use a booking platform or arrange rentals directly.
- Which buildings and amenities guests can access.
- Whether you also occupy the cottage during the year.
- Whether you need to discuss rental income protection.
Ready to Save on Cottage Insurance in Parry Sound?
Get a personalized quote in minutes.
No obligation · Average savings of 750 per year · Licensed in Ontario
Cost Factors
How Much Does Cottage Insurance Cost in Parry Sound?
A simple summer cabin and a four-season waterfront retreat won’t necessarily have the same premium. The price reflects what it would take to protect your particular property, how you use it and the coverage you choose.
As a general reference, cottage insurance can cost around $800 to $3,000 or more per year. This is a broad estimate, your premium may fall outside this range depending on your property, location, rental activity, insurer and coverage choices. Request a personalized quote to confirm your cost.
Factors insurers may consider include:
Discuss additional structures such as bunkies, garages, docks and boathouses, along with previous claims and any information required by the insurer. Your cottage’s purchase price may differ from its reconstruction cost, so ask your broker how the building value and claim settlement terms are determined.
Why Western
Why Choose Western Financial Group?
You don’t need to arrive with all the answers. A Western broker can walk you through available policies in plain language, from limits and exclusions to your responsibilities when no one is at the cottage.
Proudly BBB Accredited with an A+ Rating
We’re accredited by the Better Business Bureau (BBB), which means we meet high standards for trust, transparency, and customer service.
Advice for changing cottage plans
Cottage life changes over time. Whether you’re renovating, adding a bunkie, welcoming renters or spending more time there in winter, your broker can help you review how those plans affect your insurance needs.
Support with claims questions
Western can help you navigate the claims process and connect with the appropriate insurer contact. Your insurance company determines coverage and the claim outcome.
13,000+ Reviews Across Western | 4.5
Michael M.
Ontario, Canada
★★★★★
We contacted Western for a cottage insurance quote and had questions about our dock and bunkie. The broker walked us through the coverage and limits without rushing us
Sandra M.
Toronto, Ontario
★★★★★
Western helped us compare our cottage insurance quote with our existing policy. Looking at the deductibles and water coverage made the differences much easier to understand
Steve T.
Brampton, ON
★★★★★
We wanted to find the best cottage insurance for how we use our property. The Western broker explained the options and what we needed to check when closing up for winter.
FAQ
Frequently Asked Questions
Explore More
Other Insurance Products
Home Insurance
Protect your Ontario home, condo, or property with comprehensive coverage.
Renters Insurance
Affordable coverage for renters with protection for belongings and liability.
Business Insurance
Commercial coverage tailored to your industry and operations.
Travel Insurance
Coverage for medical emergencies, trip cancellations, and lost baggage.