


Fast · Simple · Trusted
Cottage Insurance in Kenora for Your Cabin and Seasonal Retreat
 100% Canadian Owned

13,000+ Reviews Across Western | 4.5
BUILT AROUND YOUR PROPERTY
Insurance for the Way You Use Your Kenora Property
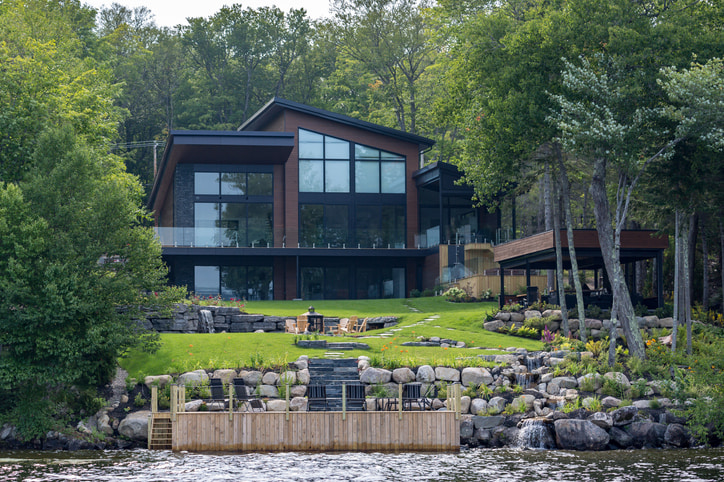
Some owners call it a cottage; others call it a cabin or camp. What matters for insurance is the property itself: how it is built, when you stay there and what happens while you are away.
For your Kenora cottage insurance quote, explain whether the property has year-round road access, is reached by boat or becomes difficult to visit outside the summer season. Include any guest buildings, docks and other structures.
A Western Financial Group broker can help you compare available options and understand the conditions attached to each policy.
Cottage Coverage
What Can Cottage Insurance Cover in Kenora?
Coverage varies by insurer. Review the protection for your building, belongings and liability, and ask which features need additional coverage.
Your cottage or cabin building
Discuss the amount needed to repair or reconstruct your cabin following an insured loss. Construction materials, renovations, custom features and access for contractors can affect the rebuilding estimate.
A covered fire damages your cabin’s kitchen and roof. Building coverage may help pay for restoration, subject to your deductible, limits and settlement terms.
Belongings kept at the property
Furniture, appliances, clothing and other contents can represent a substantial replacement expense. Ask about special limits for equipment and valuables, and how belongings brought from your primary home are insured.
An insured loss damages beds, furniture and household appliances. Contents coverage may help pay to repair or replace covered items according to your policy.
Personal Liability
Ask how your policy applies when friends, family or paying guests visit. Personal liability coverage may help with legal defence costs and covered damages if you are legally responsible for an injury or damage to someone else’s property.
A visitor is injured when an unsafe exterior step breaks. Your policy may respond if you are found legally responsible and the claim is covered.
Guest cabins and detached buildings
Identify sleeping cabins, workshops, garages and storage sheds separately. Explain how each is used, especially if guests stay overnight or the building forms part of a rental arrangement.
A covered windstorm damages a detached guest cabin. Repairs may be insured if the structure and its use are included in your policy.
Docks and boathouses
For a waterfront property in the Kenora area, confirm coverage for each dock and boathouse. Ask about insured causes of damage, valuation and any seasonal maintenance requirements. Boats and other watercraft should be discussed separately.
Coverage depends on policy terms, deductibles, limits and exclusions.
SEASONAL PROPERTY COVERAGE
Seasonal Property Insurance in Kenora
If you open your cabin for summer and close it for the colder months, explain that routine when requesting insurance. Seasonal use can affect the policy options available and the conditions you must follow while the property is unattended.

Depending on your policy, it's worth talking about:
- Your visiting schedule: When the property is occupied and how long it is left unattended.
- Winter arrangements: Whether heat remains on or the building is closed and winterized.
- Water systems: How plumbing and the water supply are managed during closure.
- Property checks: Who can inspect the cabin and how visits are recorded.
- Access changes: Whether road or boat access becomes limited during the year.
- Heating equipment: Primary and supplementary heat sources.
Ask your broker to explain the actual requirements in your policy. A neighbour checking occasionally or a general winter-closing checklist may not satisfy every insurer’s conditions.
Turning your summer cabin into a four-season retreat?
Contact your broker before changing your occupancy pattern or completing major upgrades. New heating, additional living space and more frequent use may change your coverage needs.
Rental Cottage Insurance in Kenora
Renting out your cabin—even for a few weekends—should be part of the insurance conversation before guests arrive. A policy arranged for personal use should not be assumed to cover rental activity.
Tell your Western broker:
- How often you intend to rent.
- Whether bookings are short-term or longer seasonal stays.
- Whether you use a booking platform or arrange rentals directly.
- Which cabins, buildings and waterfront features guests can access.
- Whether you also occupy the property during the year.
- Whether you want to explore rental income protection.
Ready to Save on Cottage Insurance in Kenora?
Get a personalized quote in minutes.
No obligation · Average savings of 750 per year · Licensed in Ontario
Cost Factors
How Much Does Cottage Insurance Cost in Kenora?
There is no single premium for every Kenora cottage or cabin. A small seasonal property beside a maintained road can have different insurance needs from a remote waterfront retreat with guest accommodation.
Insurers may consider:
Your cabin’s purchase price is different from its reconstruction cost. Ask how the building limit is established and whether claims are settled on a replacement cost or depreciated-value basis.
How to Find Affordable Cottage Insurance in Kenora
Western Financial Group brokers can help you compare available insurance options and identify potential savings.
? Ask about bundling: Eligible cottage, home and car policies may qualify for discounts when combined.
? Share building improvements: Provide details of roof, electrical, plumbing and heating updates.
? Discuss protective devices: Ask whether monitored alarms or water-leak sensors qualify for savings.
? Review deductible options: Choose an amount you could comfortably pay toward an insured loss.
? Compare similar protection: Check structure limits, water coverage, rental permissions and exclusions alongside the premium.
? Update your policy at renewal: Report changes to the property, occupancy and rental plans.
Why Western
Why Work With Western Financial Group?
Help comparing available coverage
A Western broker can explain policy differences and help you assess protection for the cabin and its additional structures.
Proudly BBB Accredited with an A+ Rating
We’re accredited by the Better Business Bureau (BBB), which means we meet high standards for trust, transparency, and customer service.
Advice for changing cottage plans
Cottage life changes over time. Whether you’re renovating, adding a bunkie, welcoming renters or spending more time there in winter, your broker can help you review how those plans affect your insurance needs.
Support with claims questions
Western can help you navigate the claims process and connect with the appropriate insurer contact. Your insurance company determines coverage and the claim outcome.
13,000+ Reviews Across Western | 4.5
Michael M.
Ontario, Canada
★★★★★
We contacted Western for a cottage insurance quote and had questions about our dock and bunkie. The broker walked us through the coverage and limits without rushing us
Sandra M.
Toronto, Ontario
★★★★★
Western helped us compare our cottage insurance quote with our existing policy. Looking at the deductibles and water coverage made the differences much easier to understand
Steve T.
Brampton, ON
★★★★★
We wanted to find the best cottage insurance for how we use our property. The Western broker explained the options and what we needed to check when closing up for winter.
FAQ
Frequently Asked Questions
Explore More
Other Insurance Products
Home Insurance
Protect your Ontario home, condo, or property with comprehensive coverage.
Renters Insurance
Affordable coverage for renters with protection for belongings and liability.
Business Insurance
Commercial coverage tailored to your industry and operations.
Travel Insurance
Coverage for medical emergencies, trip cancellations, and lost baggage.