


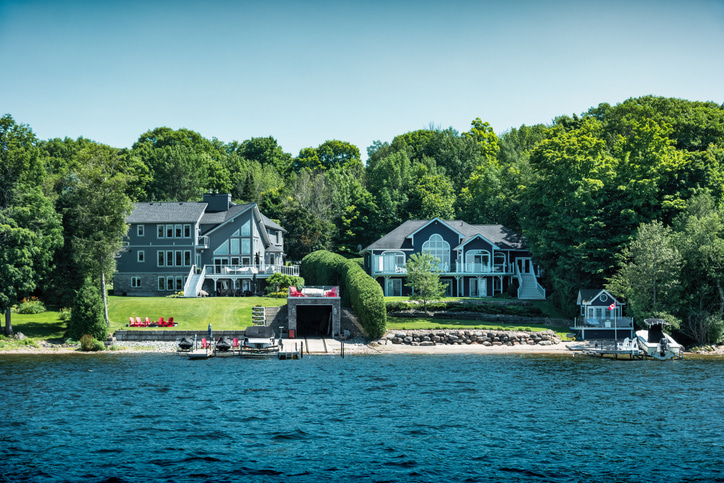
Fast · Simple · Trusted
Lake of the Woods Cottage Insurance for Your Lakeside Retreat
 100% Canadian Owned

13,000+ Reviews Across Western | 4.5
BUILT AROUND YOUR PROPERTY
Coverage That Reflects Your Lake of the Woods Property
Maybe your place is a short drive from town. Or perhaps the last leg of the trip means loading everything into a boat. Either way, insuring a Lake of the Woods cottage starts with the details that make it yours: how you reach it, who stays there and what’s left behind when you head home.
Start with the main cabin, then think about the bunkie everyone wants to sleep in, the shed full of gear and the dock or boathouse at the water’s edge. Your broker will also need to know when you visit and who looks after the property between stays.
Those conversations help your Western broker narrow down available options and explain what each policy expects of you. You don’t need to know all the insurance terms before you call.
Cottage Coverage
What Can Lake of the Woods Cottage Insurance Cover?
There’s more to your property than the cabin itself. Work your way from the kitchen to the shoreline and check what’s included at each stop. Policies differ by insurer, and the main building limit shouldn’t be assumed to protect everything on the site.
Your cottage or cabin
If you had to rebuild, what would it take to put your cottage back the way it was? Construction, renovations, finishes and the logistics of getting work done on-site all matter. Building coverage may help pay for repairs or reconstruction after an insured loss, subject to your policy.
For an island property, ask how transporting workers, equipment and materials is considered when establishing the insured value. If a covered fire damages your cabin’s kitchen and roof, building coverage may help pay for restoration, subject to your deductible, limits and settlement terms.
Furniture and personal belongings
Beds, furniture, appliances, clothing: replacing what stays at the cottage can add up faster than you’d think. Review contents limits, including special limits for valuables and equipment. For the bags you bring each weekend, ask how your cottage and primary home policies treat those belongings. If an insured loss damages your cottage furniture and appliances, contents coverage may help pay to repair or replace eligible items according to your policy.
Personal liability
A full cottage usually means extra shoes at the door and another chair at the table. It also brings responsibilities. Personal liability coverage may help with legal defence costs and covered damages if you’re legally responsible for someone’s injury or damage to their property.
Explain the activities and amenities available to visitors, particularly if paying guests use the property. If a guest is injured when an unsafe exterior step breaks, your policy may respond if you are found legally responsible and the claim is covered.
Guest cabins and detached buildings
That little bunkie deserves its own mention, even if it’s only used a few weekends a year. Identify guest cabins, workshops, garages and storage sheds separately, explain how each is used and confirm its coverage limit. Sleeping space and rental accommodation need particular attention. If a covered windstorm damages an insured guest cabin, repair costs may be covered, subject to the policy’s terms and permitted use.
Docks and boathouses
Down at the shoreline, the dock may be your front entrance as much as your favourite place to sit. Don’t assume that makes it automatically insured. Check which causes of damage are covered, how the dock is valued and whether maintenance or seasonal removal conditions apply.
Review boathouses separately, including any belongings stored inside. Do not assume boats, motors or other watercraft are covered by the building’s insurance.
Seasonal Property Insurance for Lake of the Woods Cottages
The last weekend of the season has a different rhythm: empty the fridge, pack the linens and make one more round before locking up. Your insurance needs to fit that routine, too. Explain when you open and close the cabin and how it’s looked after while no one is there. Available seasonal property coverage depends on the building, its use and those arrangements.

Before closing for the season, ask about:
- Heating requirements if the building remains heated.
- Water shutoff and plumbing winterization conditions.
- Required inspections or property checks.
- Security arrangements and belongings left behind.
- What to do if access prevents a scheduled check.
Your own policy sets the requirements. A familiar winter-closing checklist, or an occasional visit from a neighbour, may not be enough. Confirm the details with your broker before you leave for the season.
Rental Cottage Insurance at Lake of the Woods
Thinking about renting out a few weeks you won’t use? Before the calendar fills up, check your insurance. Even occasional paying guests can change how the property is assessed, and you shouldn’t assume a personal-use policy covers rental stays.
Tell your broker:
- How often the cottage will be rented.
- Whether bookings are short-term or longer seasonal stays.
- Whether you rent through a platform or directly.
- Which cabins, docks and other amenities guests can access.
- Whether equipment or watercraft are included.
- Whether you also occupy the property during the year.
Ready to Save on Cottage Insurance in Lake of the Woods?
Get a personalized quote in minutes.
No obligation · Average savings of 750 per year · Licensed in Ontario
Cost Factors
How Much Does Cottage Insurance Cost at Lake of the Woods?
A small roadside cabin and an island retreat with a guest bunkie won’t necessarily cost the same to insure. Your premium depends on the property, how you use it and the coverage you choose. A quote based on your own details is more useful than a one-size-fits-all estimate.
One distinction is easy to miss: what you paid for the cottage isn’t the same as what it would cost to rebuild. Discuss a building limit that reflects reconstruction, including the work involved in getting materials and crews to your site.
Discuss rental activity and frequency, additional structures such as guest cabins, sheds, docks and boathouses, coverage limits, optional protection, deductibles and previous claims or other information required by the insurer.
Ways to Find Affordable Cottage Insurance
Of course you’d rather put the savings toward another weekend at the lake. A lower premium is worth exploring, as long as you know what you’re keeping and what you’re giving up. Start with these questions for your Western broker.
Start with these questions for your Western broker.
- Compare suitable options: Ask a Western broker to review available policies with comparable protection.
- Explore bundling: Combining eligible cottage, home and car insurance may qualify for discounts.
- Share improvements: Report updates to your roof, electrical, plumbing and heating systems.
- Discuss protective equipment: Ask whether monitored alarms or water-leak detection devices qualify for savings.
- Choose a manageable deductible: Consider what you could comfortably pay following an insured loss.
- Review coverage at renewal: Update your broker about renovations, rental plans and changes in occupancy.
Why Western
Why Work With Western Financial Group?
Help understanding available coverage
You know your cottage. We can help with the insurance language. Your Western broker can explain limits, exclusions and deductibles so you can compare available protection for the main cabin and the structures around it.
Advice as your property changes
Maybe you’re finally renovating the kitchen, adding a bunkie or making room for more winter visits. Bring your broker into the conversation before renovations, rentals or a change in your seasonal routine so you can review what those plans mean for coverage.
Proudly BBB Accredited with an A+ Rating
We’re accredited by the Better Business Bureau (BBB), which means we meet high standards for trust, transparency, and customer service.
That commitment has earned us national and regional recognition across employer culture, customer experience, innovation, and social impact. Our awards reflect the quality of our service, the strength of our team, and the depth of our engagement in communities coast to coast.
13,000+ Reviews Across Western | 4.5
Michael M.
Ontario, Canada
★★★★★
We contacted Western for a cottage insurance quote and had questions about our dock and bunkie. The broker walked us through the coverage and limits without rushing us
Sandra M.
Toronto, Ontario
★★★★★
Western helped us compare our cottage insurance quote with our existing policy. Looking at the deductibles and water coverage made the differences much easier to understand
Steve T.
Brampton, ON
★★★★★
We wanted to find the best cottage insurance for how we use our property. The Western broker explained the options and what we needed to check when closing up for winter.
FAQ
Frequently Asked Questions
Explore More
Other Insurance Products
Home Insurance
Protect your Ontario home, condo, or property with comprehensive coverage.
Renters Insurance
Affordable coverage for renters with protection for belongings and liability.
Business Insurance
Commercial coverage tailored to your industry and operations.
Travel Insurance
Coverage for medical emergencies, trip cancellations, and lost baggage.