
 13,000+ Reviews | 4.5
Quick answer
A standard home insurance policy in BC does not cover overland flooding, meaning water that enters your home from an overflowing river, the ocean or surface runoff. You need an optional overland water (flood) endorsement for that, and a separate sewer backup endorsement for water that comes up through your drains.
In Surrey, homes in the coastal floodplain (including Crescent Beach, Mud Bay and the Nicomekl and Serpentine lowlands) and near the Fraser River in South Westminster should review both coverages, along with their limits and deductibles, before the fall and winter storm season.
Why flood insurance matters in Surrey
Surrey is surrounded by water. The city's coastal floodplain alone covers about 20% of its land area, running from Boundary Bay and Mud Bay along the Nicomekl and Serpentine Rivers toward Cloverdale and Newton. To the north, the Fraser River runs along about 22 km of Surrey's boundary.
Much of this land is protected by dikes, sea dams, pump stations and drainage ditches. The sea dams on the Nicomekl and Serpentine Rivers date back to 1912 and 1913. The city and province are still investing in that system. In August 2026, the province announced funding to replace culverts and raise the dike along the Nicomekl River, along with new and upgraded drainage pump stations on the Serpentine, with work scheduled for completion in 2027.
The infrastructure here reduces risk, but it doesn't eliminate it, and it doesn't change what your insurance policy covers.
When is flood season in Surrey?
Surrey faces two flood seasons:
- Fall and winter: Atmospheric rivers frequently hit BC's south coast in fall and winter, bringing heavy rain that can overwhelm creeks, ditches and storm drains. High tides and storm surges can add to the risk in coastal areas.
- Spring and early summer: The Fraser River freshet, driven mainly by mountain snowmelt, typically peaks in spring and early summer. South Westminster, a very low area near the Pattullo Bridge, has historically flooded during the freshet.
The November 2021 atmospheric river was a reminder of how serious BC flooding can be: it caused five deaths and severe damage across the Fraser Valley. More recently, flooding in southwestern BC in December 2025 led the province to open Disaster Financial Assistance applications for affected residents.
Does home insurance cover flooding in BC?
In most cases, no. A standard home policy usually covers sudden water damage that starts inside your home, but it typically excludes water that comes from outside. Here's how the main types of water damage are usually handled:
- Burst pipe or appliance leak inside the home: Usually covered in most standard policies.
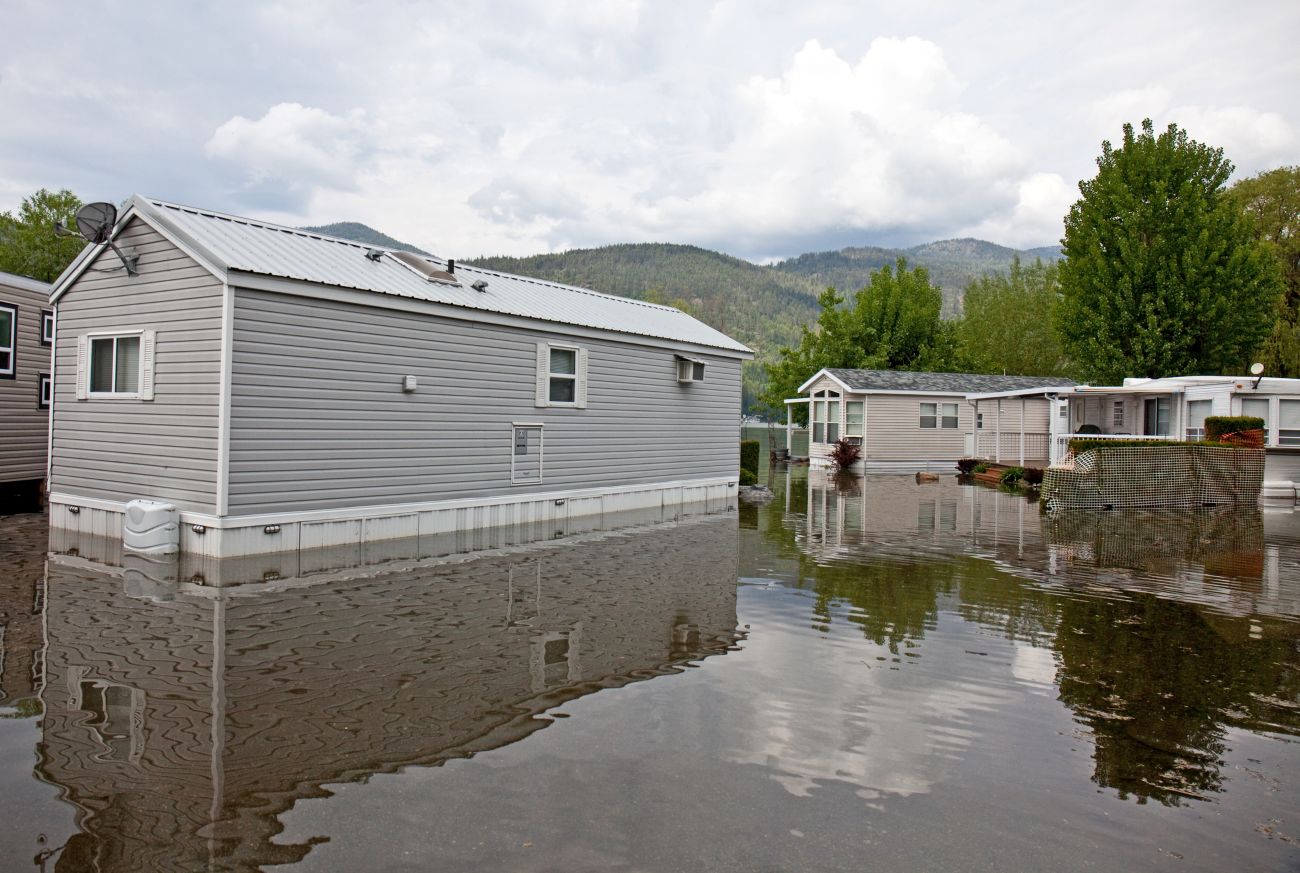
- Overland flood (river, ocean or surface runoff entering the home): Not covered. Add an overland water or flood endorsement.
- Sewer backup (water coming up through floor drains, toilets or sinks): Not covered. Add a sewer backup endorsement.
- Groundwater seeping through the foundation: Usually not covered, and availability is limited. Ask your broker.
- Gradual leaks, seepage or poor maintenance: Not covered. Address these through regular maintenance.
Many insurers in BC do now offer overland water coverage, but availability, limits and price depend on how close your home is to a river or the ocean, its elevation and the protection around it. Always check your policy wording and review your options with Western Financial Group, your local insurance broker.
For a broader look at how this coverage works, read why overland flood insurance matters.
What's the difference between overland flood and sewer backup?
Overland flood is water that flows over the ground and into your home, for example the Nicomekl or Serpentine overflowing, ocean water reaching a coastal property, or heavy rain pooling and running into a basement.
Sewer backup is water that comes up through your floor drains, toilets or sinks when the municipal sewer or storm system is overwhelmed. It can happen during an atmospheric river even if you live nowhere near the water.
In a major storm, you can experience both at once. That's why most brokers recommend carrying both endorsements, with limits high enough to cover a finished basement and any basement suite.
Not sure what's on your policy? Western Financial Group can help!
Get a free, no-obligation quote and a Surrey broker will check your water coverage and compare options across insurers.
Which Surrey neighbourhoods have higher flood risk?
Flood risk is property-specific, but areas the City of Surrey identifies as floodplain include:
- The coastal floodplain: Crescent Beach, Mud Bay, Colebrook, Panorama/Gray Creek, Nico-Wynd/Crescent Road and the inter-river area between the Nicomekl and Serpentine. Coastal areas here are strongly influenced by ocean tides and weather.
- The Serpentine and Nicomekl lowlands: Mostly farmland, much of it close to sea level, stretching toward Cloverdale.
- The Fraser River floodplain: Including South Westminster near the Pattullo Bridge, an area with a mix of homes and industrial properties behind the river dikes.
- The Little Campbell River area: Near White Rock and Semiahmoo First Nation.
Learn more on the City of Surrey's lowlands and floodplains page, then talk to your broker about what your location means for your coverage.
Do I need flood coverage if I have a basement suite?
Basement suites are common in Surrey, and they're often the first part of a home to flood. If you rent out a suite, check that:
- Your insurer knows about the suite and your tenants.
- Your overland water and sewer backup limits are high enough to cover the suite's finishes, kitchen and flooring.
- Your policy includes coverage for lost rental income if the suite becomes unlivable after a covered claim.
- Your tenants know your policy doesn't cover their belongings. They need their own tenant insurance, ideally with water endorsements.
What about condos and townhouses?
Your strata's policy covers the building, but it may carry a large water or flood deductible, and owners can be charged a share of it. Your own condo insurance can cover your belongings, your unit's improvements and, in many cases, your share of a strata deductible. Ask your broker whether your policy includes water and flood coverage for your unit.
What should I check on my policy before storm season?
- Do I have overland water coverage? Look for an endorsement named overland water, flood or similar.
- Do I have sewer backup coverage? It's a separate endorsement on most policies.
- What are the limits? Many endorsements have a sub-limit lower than your dwelling coverage. Make sure it would cover a finished basement, a basement suite and their contents.
- What's the deductible? Water endorsements often carry a separate, higher deductible.
- Are there conditions? Some insurers require a backwater valve or sump pump for sewer backup coverage.
How can I protect my Surrey home from flooding?
- Install a backwater valve and a sump pump with battery backup.
- Clear leaves from eavestroughs, downspouts and the storm drain in front of your home before fall rains.
- Make sure the ground slopes away from your foundation and downspouts discharge well away from the house.
- Keep valuables, documents and electronics off the basement floor.
- Keep a photo or video inventory of your belongings, stored in the cloud.
- Watch for flood watches and warnings from the BC River Forecast Centre and follow City of Surrey alerts during storms and freshet season.
For a full checklist, see how to protect your home from a flood.
Won't government disaster assistance cover me?
Don't count on it. BC's Disaster Financial Assistance (DFA) program is for uninsurable losses. It doesn't cover losses where insurance was reasonably and readily available, and it doesn't cover insurance deductibles. When DFA is approved for an event, it covers 80% of eligible damage above $1,000, up to a maximum of $400,000, and only for your principal residence. Damage to belongings in basements is excluded unless the space was used as essential living space.
Where overland flood coverage is available to you, it's generally the more reliable protection. Learn more on the Government of BC's Disaster Financial Assistance page.
Surrey flood insurance FAQs
Does home insurance cover flooding in Surrey?
A standard home insurance policy does not cover overland flooding from rivers, the ocean or surface runoff. You need an optional overland water (flood) endorsement. Sewer backup also requires its own endorsement.
How much does flood insurance cost in Surrey?
The cost depends mainly on your home's flood risk, including its distance from rivers and the ocean, its elevation and local flood protection, plus the limit and deductible you choose. A broker can compare prices from several insurers for your address.
Can I get flood insurance in Crescent Beach or Mud Bay?
Often yes, but availability, limits and price vary by insurer and property. Homes in higher-risk coastal areas may face higher premiums or lower limits, and some may not qualify. A broker can check what's available for your address.
What is the difference between overland flood and sewer backup insurance?
Overland flood covers water entering your home from outside, such as an overflowing river or ocean flooding. Sewer backup covers water coming up through your drains when the sewer or storm system is overwhelmed. They are separate endorsements.
When is flood season in Surrey?
Surrey's highest-risk periods are fall and winter, when atmospheric rivers bring heavy rain and high tides, and spring to early summer, when the Fraser River freshet peaks.
Does tenant or condo insurance cover flooding?
Not automatically. Renters and condo owners can usually add overland water and sewer backup endorsements to protect their belongings and improvements. Condo owners should also check their strata's water deductible.
Can I add flood insurance right before a storm?
Some insurers won't add or increase flood coverage when a flood is imminent or a warning is in effect. Review your coverage well before storm season.
Talk to a local Western broker
Not sure if you're covered for flooding? Western Financial Group's Surrey brokers can review your home, condo or tenant policy, explain your water coverage in plain language, and compare options across insurers. Visit us at Sunshine Hills, Semiahmoo, Cloverdale, Grandview Corners or Clayton Crossing, or learn more about home insurance in Surrey.
This article is general information only and isn't insurance, legal or financial advice. Coverage depends on your insurer and the wording of your policy. Talk to a licensed broker about your situation.